
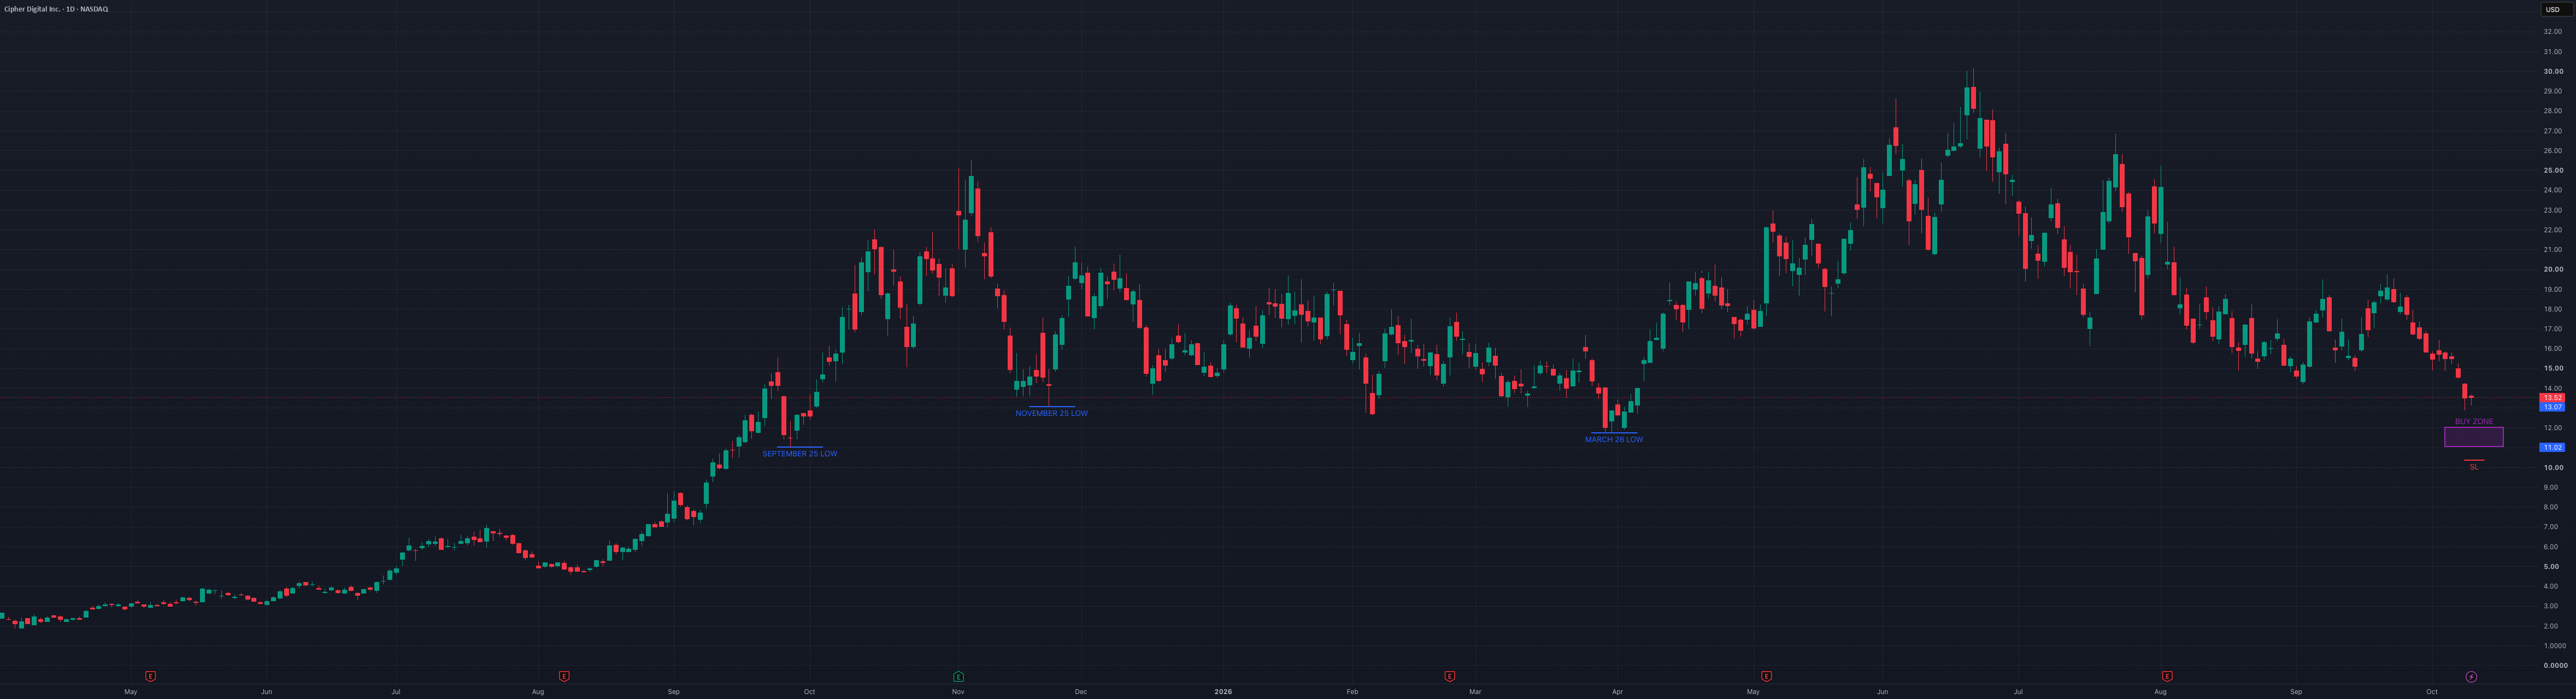
Cipher Digital (formerly Cipher Mining) has fallen since its June high. The sell-off was mainly driven by macro factors. Inflation concerns and expectations of further rate hikes pushed bond yields to multi-decade highs, which weighs heavily on debt-financed, rate-sensitive names like CIFR. The OpenAI revenue report and a weaker Bitcoin added pressure on the sector.
In my view, the OpenAI reaction was partly overdone. Much of the gap came from comparing OpenAI’s net revenue with peers that report gross revenue, including sales through cloud partners. It does not mean OpenAI lost sales.
Chart:
– Downtrend since June with lower highs. Price is below all major moving averages.
– Price found a bottom at the Sep 25 low (~11.05 USD), the Nov 25 low (~13.10 USD) and the Mar 26 low (~11.74 USD).
– Price is currently testing the Nov 25 low (~13.10 USD). Friday’s low was 13.12 USD, so the level has held so far, but the reaction is still weak.
– My buy zone (~11 to 12 USD) ranges from the lowest candle close around the Mar 26 low down to the wick of the Sep 25 low.
Levels I’m watching:
– A daily close above the recent highs would be a first constructive signal that the Nov 25 low holds.
– If it breaks, I expect a move into the buy zone at ~11 to 12 USD.
– A daily close below ~10.40 USD would invalidate the technical setup.
Fundamentals (per Cipher’s Q2 2026 business update and investor presentation):
– 700 MW of contracted gross HPC capacity under long-term leases (10 to 15 year base terms).
– ~$11.4B in contracted revenue.
– Contracted leases target ~$793M in average annualized NOI from Oct 2026 to Sep 2036. Q2 revenue was only $24.8M, all from Bitcoin mining.
– First capacity at Black Pearl was delivered two months ahead of schedule, rent started in August. At Barber Lake, rent is expected to begin in October.
– ~5.3 GW portfolio capacity across 11 sites by 2030+, including a new option for up to 900 MW near San Antonio. Pipeline capacity is subject to the ERCOT batch process.
Analyst view:
– Morgan Stanley cut its price target to $51.50 from $54 but kept its Overweight rating.
Catalyst:
Q3 earnings around Nov 10 will be the first quarter with lease revenue. It will show whether the shift to a data center landlord model is on track.
Risks:
– Around $5.5B in borrowings (as of June 30). Higher rates raise financing costs and lower the value of long-dated lease income.
– Fed minutes indicate officials expect another rate hike before year-end.
– Weaker AI demand would also put pressure on tenants.
Macro risks:
– CIFR is a high-beta stock and reacts strongly to macro and geopolitical news.
– The ongoing Middle East conflict keeps oil prices elevated. Higher oil prices can fuel inflation, push yields higher and put further pressure on rate-sensitive names like CIFR.
– Geopolitical escalation can invalidate any technical setup at any time.
– The US midterms on Nov 3 and Q3 earnings around Nov 10 fall within roughly one week. I expect elevated volatility around both events.
Disclosure: I already hold a starter position in CIFR. I consider this entry early given the current downtrend. This is my personal analysis, not a recommendation. Always do your own research.