
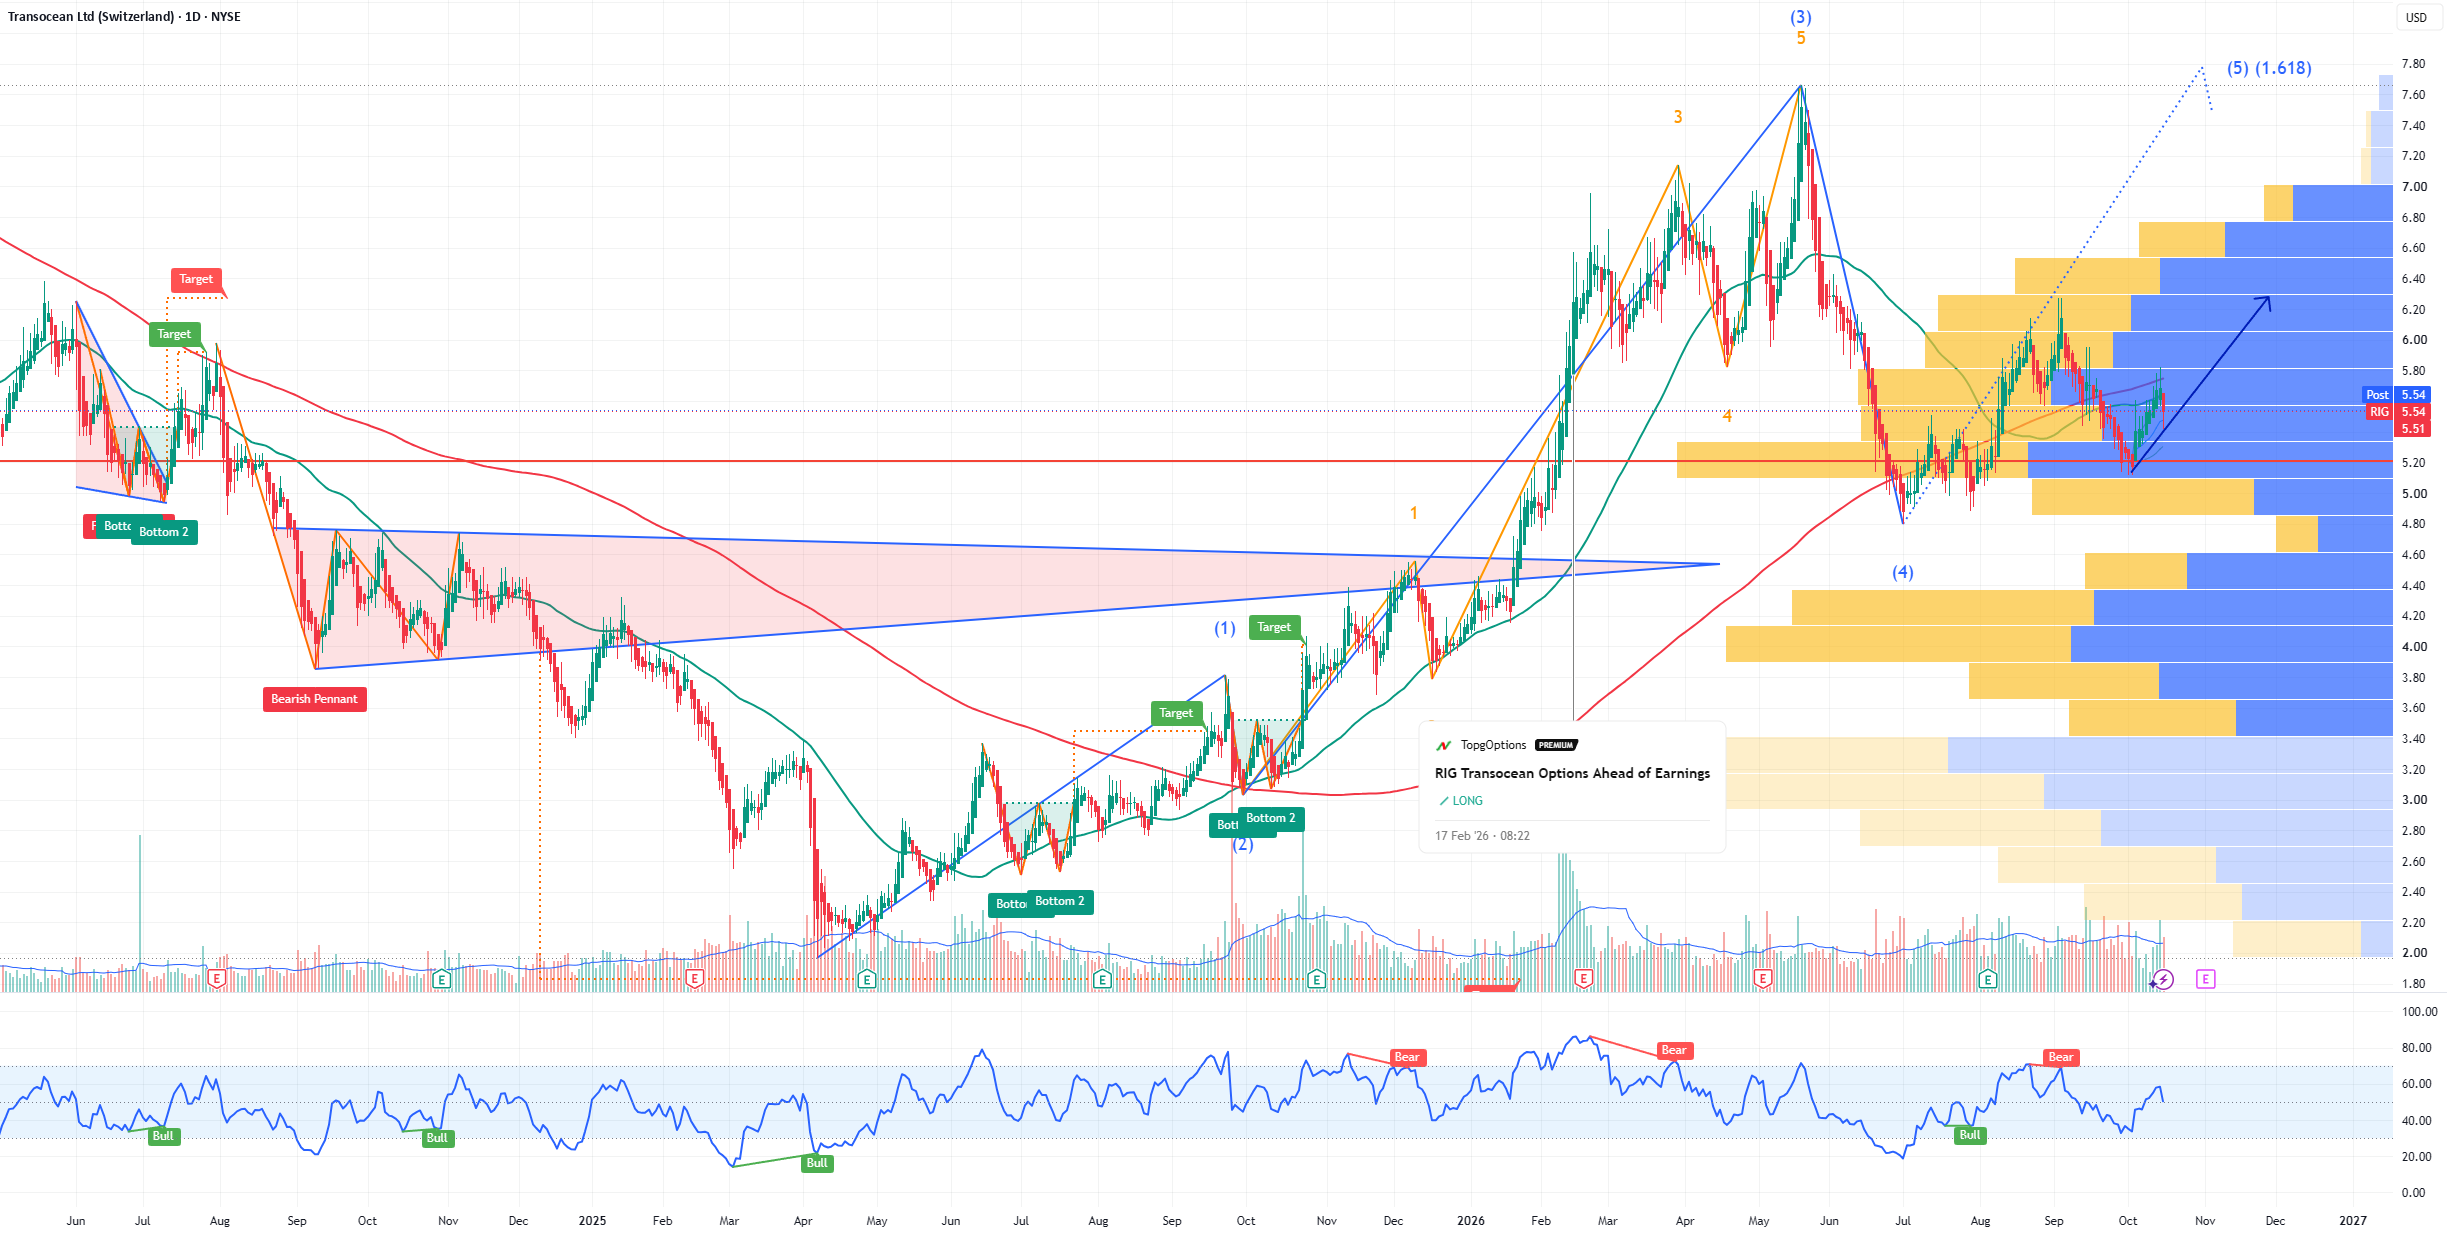
Transocean is strengthening its position in a tightening offshore drilling market through recent contract wins that expand firm backlog, while its pending all-stock acquisition of Valaris advances toward a potential Q4 2026 close.
High utilization on high-spec rigs and improving visibility into cash flows support further upside as the cycle matures.
Recent backlog additions of approximately $1.1 billion include final approval converting the ~$1 billion Equinor agreement (three harsh-environment semisubmersibles offshore Norway) into firm backlog, plus a new ~$62 million two-well Shell contract for Transocean Norge; total contract backlog now exceeds $7.7 billion, providing multi-year revenue visibility.
The all-stock acquisition of Valaris continues to progress, with Brazil’s CADE issuing an unrestricted approval decision (subject to a short waiting period) and other regulatory conditions largely cleared; expected close in Q4 2026 could deliver $200M+ in synergies, a larger and more diversified fleet, and accelerated deleveraging.
Industry fundamentals remain supportive: limited supply of modern ultra-deepwater and harsh-environment rigs, firm day rates, and management’s outlook for near-100% utilization on deepwater assets by 2027, driven by demand in the U.S. Gulf, Brazil, West Africa, and Norway.
Balance-sheet actions continue, including retirement of higher-cost notes and preparation of an expanded revolving credit facility contingent on the Valaris close, which should support lower interest expense and improved free cash flow conversion from the growing backlog.
Analyst consensus is Buy/Hold with average price targets in the $6.5–6.7 range (modest upside from recent levels near $5.5), while higher targets (up to $10) reflect the potential for a re-rating if the merger closes smoothly and day-rate strength persists.